Sales Are Strong but Cash Feels Tight
Customer invoices may be recorded as revenue before the cash reaches the bank account.
- Slow customer collections
- Large supplier payments
- Payroll before receipts
- Tax payments between sales cycles
Cash Flow Forecasting in Surrey BC helps business owners when sales look healthy but the bank balance still feels unpredictable. You may be worried about payroll, suppliers, GST/HST, loan payments, or committing to a hire or equipment purchase without knowing whether enough cash will be available when each payment is due.
Phoenix Knight Financial Services turns records into a cash plan. We review opening cash, customer collections, supplier payments, payroll, taxes, debt, seasonal changes, and planned spending. With more than 20 years of experience, Phoenix Knight helps Surrey businesses compare short-term pressure and longer-term needs before cash decisions become urgent.
A business can report revenue and profit while still having difficulty meeting upcoming payments. Customer collections, payroll, supplier bills, taxes, debt payments, and growth spending may all happen at different times.
Customer invoices may be recorded as revenue before the cash reaches the bank account.
A forecast can identify weeks or months where expected payments are higher than expected cash receipts.
Hiring, inventory, equipment, marketing, and expansion can require spending before the related revenue is collected.
Forecasting combines expected receipts and payments so owners can see where cash pressure may develop before relying only on the current bank balance.
The right forecast depends on the question. A weekly forecast helps manage near-term payment timing, while a longer projection can support budgets, growth decisions, financing discussions, and seasonal planning.
A weekly view is useful when timing matters and upcoming obligations need closer attention.
A monthly view helps owners compare seasonal patterns, planned investments, financing requirements, and larger business decisions.
The weekly model starts with available cash, adds expected receipts, subtracts expected payments, and shows the projected closing balance for each period.
Start with the available bank balance and other relevant short-term cash information.
Estimate when customer payments, deposits, recurring receipts, and other expected inflows may reach the business.
Map payroll, suppliers, rent, taxes, debt, insurance, software, and planned purchases to their expected payment dates.
Calculate the expected ending position and flag periods where cash may become tighter than planned.
As actual receipts and payments become known, replace estimates with actual results and add another future period so the forecast remains useful.
Some business decisions need more than a weekly view. A 12-month projection can organize expected revenue, recurring expenses, large purchases, financing, and other planned cash movements across the year.
Review when customer payments are expected rather than assuming revenue arrives evenly throughout the year.
Map large and recurring expenses to the periods when cash is expected to leave the business.
Compare expected cash with the cost and timing of new hires, equipment, marketing, inventory, or expansion.
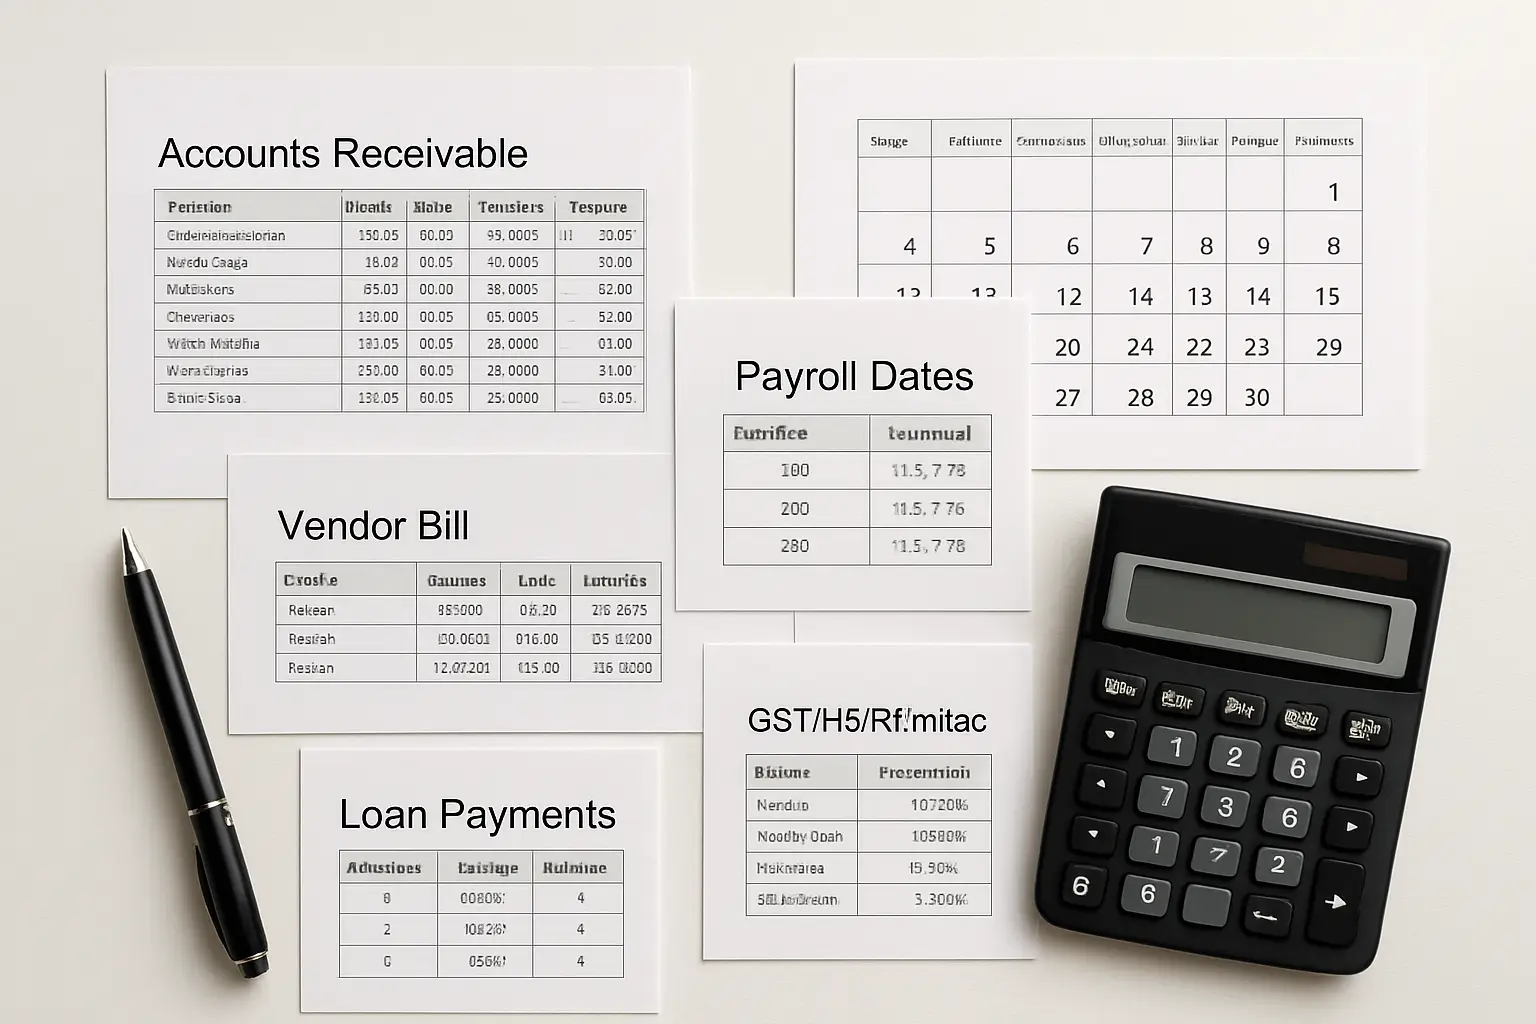
Forecast accuracy depends on the information behind the model. Customer balances, supplier bills, payroll dates, debt payments, and tax-related obligations should be reviewed before they are placed into the forecast.
Working-capital pressure can develop when customers pay slowly, inventory sits too long, or supplier payment timing does not match the business's collection cycle.
Review when customers are expected to pay and which balances are creating the largest timing gaps.
Product-based businesses may have cash tied up in purchases long before inventory turns back into customer receipts.
Review supplier due dates and how those commitments fit with expected customer collections.
A single forecast shows one set of assumptions. Scenario planning can show how cash may change if sales, collections, hiring, equipment spending, or other important inputs change.
Start with the assumptions management currently considers most reasonable for receipts and payments.
Test what stronger sales may require in staffing, inventory, equipment, working capital, and operating cash.
Test weaker collections, delayed projects, lost revenue, higher costs, or other conditions that could reduce available cash.
Actual receipts and payments can differ from assumptions. Forecasts should be updated as better information becomes available.
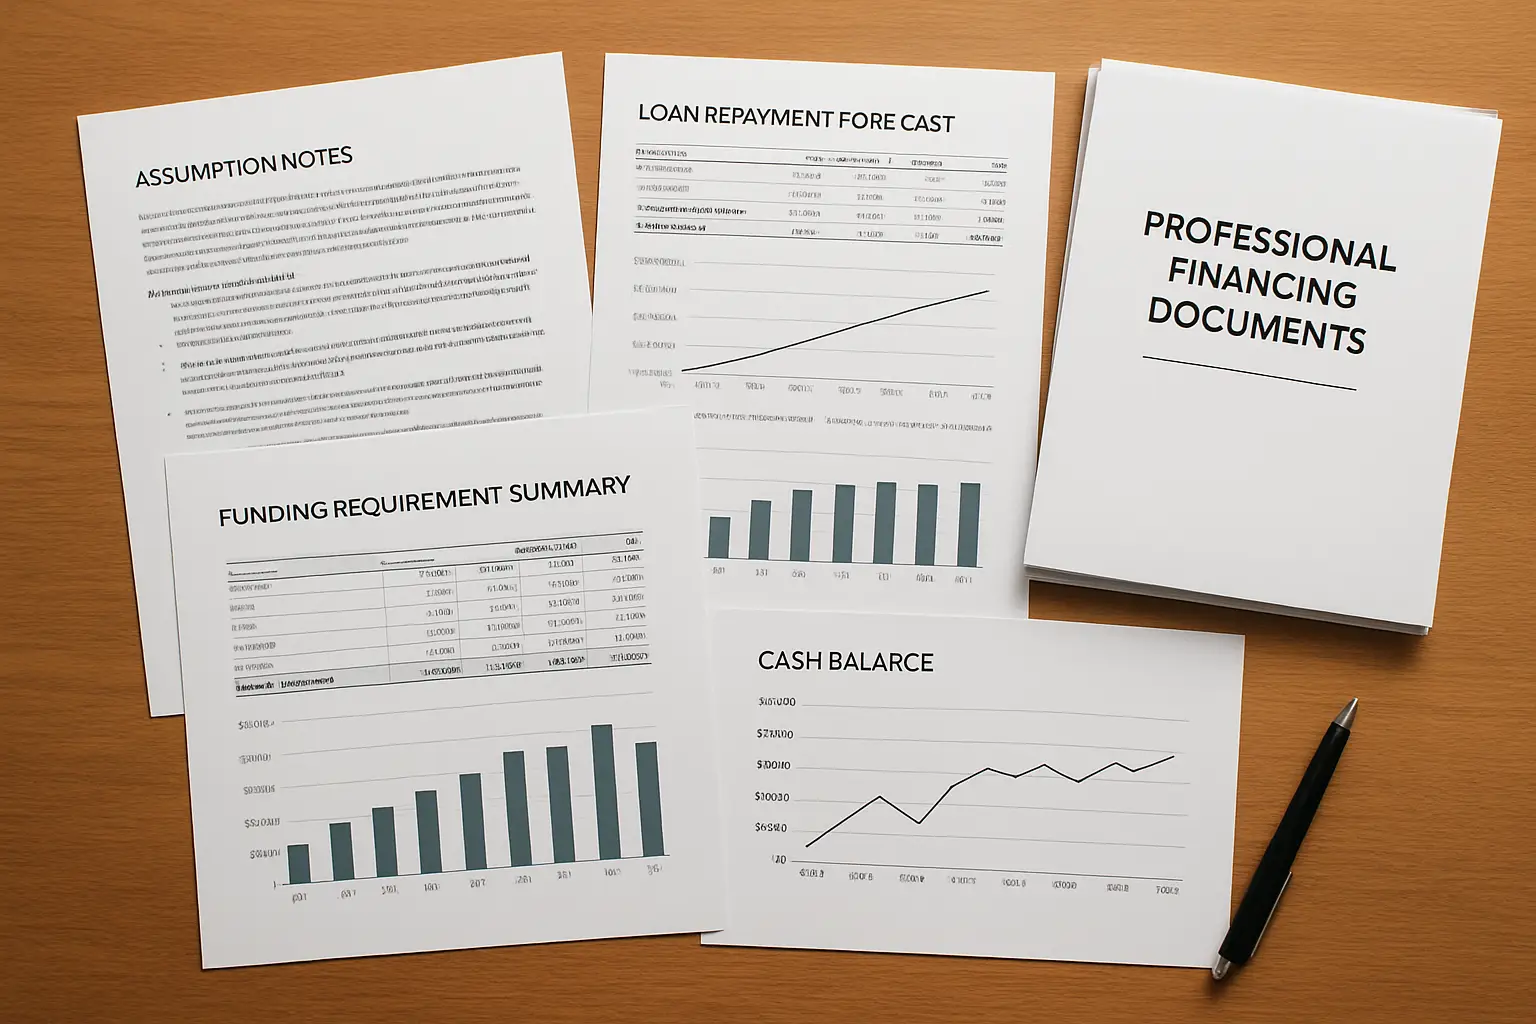
A financing discussion may require the business to explain why funding is needed, when cash pressure occurs, how the funds may be used, and how future business activity could affect cash.
Forecasting can support financing preparation, but it does not guarantee approval. Lenders and financing providers determine their own eligibility and approval requirements.
A forecast is more useful when a projected cash gap leads to a decision. The appropriate response depends on the cause of the timing problem and the options available to the business.
Forecasting works best as a living planning process. Comparing actual activity with earlier assumptions can show which collections, payments, or business decisions need to be updated.
Replace completed forecast periods with the actual receipts and payments that occurred.
Adjust expected collections, supplier payments, payroll, taxes, and planned spending as conditions change.
Identify which receipts or payments differed materially from the earlier forecast.
Decide which upcoming cash risks, spending decisions, or collection issues need attention.
Cloud accounting can make bank activity, receivables, payables, and other financial information easier to review alongside the forecast.
Explore Cloud Accounting SolutionsThe forecast should reflect how the business actually collects revenue and pays costs rather than using the same assumptions for every industry.
Project businesses may need to plan around progress billing, holdbacks, subcontractors, materials, equipment, and delayed customer collections.
Explore Contractor Accounting ServicesRetail businesses may need to compare inventory purchases, seasonal sales, supplier terms, merchant deposits, rent, and payroll.
Service businesses may need to forecast invoice timing, retainers, contractor costs, payroll, project expenses, and customer collection delays.
When the business is already under cash pressure, the immediate priority is understanding available cash and the obligations coming due before building a longer forecast.
If account balances, receivables, payables, or other financial records are unclear, the underlying accounting may need review before the forecast can rely on those numbers.
Explore Professional Accounting ServicesForecasting scope depends on the business's current records, cash pressure, planning horizon, transaction complexity, and the decisions the forecast needs to support.
Near-term cash pressure may require a weekly model, while broader planning may need a longer monthly view.
Unclear receivables, payables, bank balances, or bookkeeping may require review before forecasting begins.
Payroll, debt, inventory, projects, seasonal revenue, or multiple locations can create additional forecast inputs.
Hiring, financing, expansion, equipment, seasonal planning, and immediate cash pressure may require different scenarios.
Phoenix Knight supports Surrey businesses with short-term cash forecasting, annual projections, working-capital reviews, scenario planning, financing projections, and cash-pressure analysis.
Explore the Surrey Service AreaFind answers about 13-week forecasts, annual planning, hiring, financing preparation, update frequency, accounting records, and cash pressure.
Cash flow forecasting estimates when money may enter and leave the business so owners can compare expected receipts, payments, and projected cash balances before upcoming obligations arrive.
A 13-week model gives a weekly view of expected collections, payroll, suppliers, taxes, debt payments, and closing cash. It can be useful when short-term timing needs closer attention.
A longer forecast can support seasonal planning, annual budgeting, hiring, equipment purchases, financing needs, expansion, and other decisions that extend beyond the next few weeks.
A forecast can add wages and other expected employment costs to the planned cash outflows and compare them with expected collections and other obligations before the hiring decision is made.
Cash projections can organize expected receipts, operating payments, debt obligations, funding needs, projected balances, and assumptions for financing discussions. Financing approval remains the lender's decision.
The update schedule depends on how quickly conditions change. Businesses with tighter cash or uncertain collections may need more frequent updates, while a more stable business may use a less frequent review schedule.
No. A forecast is based on available information and assumptions. Its usefulness comes from showing likely timing and being updated as actual results become available.
Yes. Phoenix Knight provides cash flow forecasting support for businesses in Surrey, British Columbia.
Forecasting may need to connect with tax-related payments or broader service support depending on the financial information used in the model.
Bring your current cash balance, upcoming bills, payroll dates, expected customer payments, tax-related obligations, debt payments, and the decision you are trying to make.
The initial review can help identify whether the next step is a short-term forecast, a longer projection, a scenario comparison, or clearer accounting information.
Contact Phoenix Knight